



After the introduction of the battery consumption tax: How should PACK manufacturers calculate their “costs”?
On September 1, 2026, lithium-ion batteries officially bid farewell to the 11-year tax-free era, and the consumption tax will be levied at the 2% tax rate. From September 1, 2027, the tax rate will rise to 4%.. For PACK factories and downstream equipment manufacturers, this is not a simple "price increase" problem, but a re-sorting of the cost structure.
First, look at the boundary of the tax base. According to industry agency estimates, the consumption tax corresponding to the cell link is about 0.00648 yuan/Wh, and the PACK link is about 0.00071 yuan/Wh.. This means that the value division between cell and PACK directly determines which link the tax burden falls on. Purchased taxable batteries continuously produce taxable batteries, which avoids double taxation, but also puts forward higher requirements for the procurement management of PACK factories..
Take a device equipped with 50kWh battery as an example. The cost increased by about 500 yuan at battery pack of the tax rate and 960 yuan at 4% of the tax rate.. The number is not large, but for manufacturers with an annual output of tens of thousands of sets of equipment, the cumulative impact is considerable.
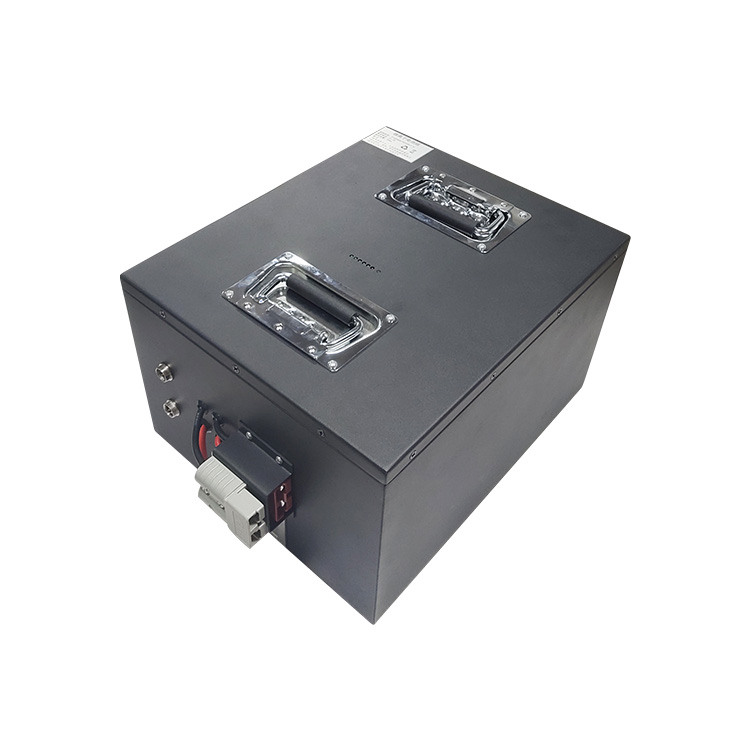
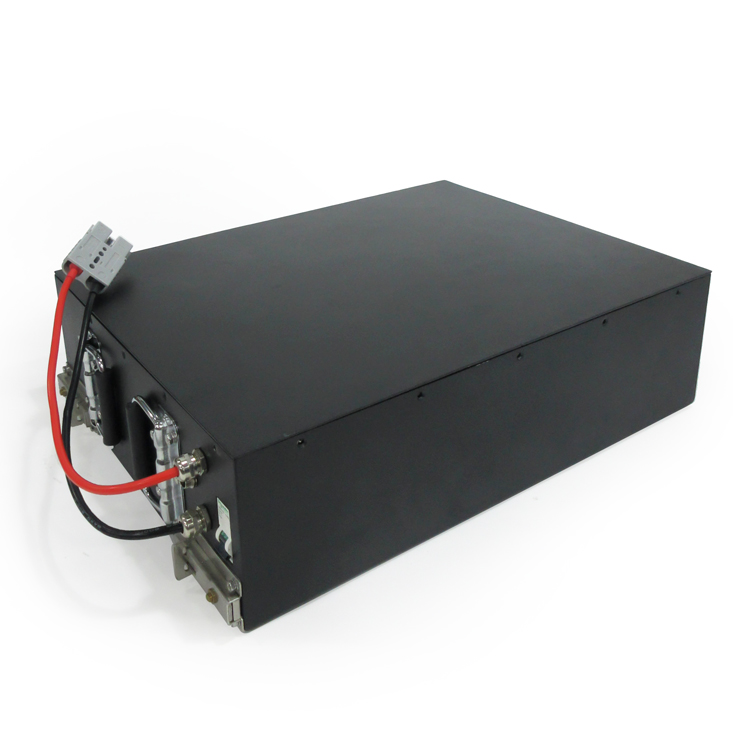
The countermeasures of Dongguan Juneng New Energy Technology Co., Ltd. on this matter are worth reference. The company's flexible manufacturing system with an average daily production capacity of more than 70 sets enables it to flexibly adjust the cell purchase batch and PACK assembly rhythm according to customer orders. In the incoming inspection process, full inspection and capacity distribution shall be carried out for cell, and the capacity deviation shall be controlled within 1% to avoid additional losses caused by improper allocation of cell. In the design of BMS, we adopt the method of "One scenario one strategy" to prolong the cycle life of the battery through accurate charge and discharge management, and help customers dilute the cost increment brought by consumption tax from the perspective of the whole life cycle.
It is worth noting that the policy gives phased tax exemption support to sodium ion batteries and solid-state batteries until the end of 2028, which leaves a buffer space for PACK factory when the system is switched cell.. For equipment manufacturers, P is evaluated against the background of consumption tax levy. ACK partner, a pragmatic judgment standard is: whether the other party can provide cost reduction solutions at the same time in the three dimensions of cell selection, BMS strategy and manufacturing process.

 Dongguan Juneng New Energy Technology Co., Ltd.
 137 5142 6524(Miss Gao)
 susiegao@power-ing.com
 Xinghuiyuan High tech Industrial Park, Dalang Town, Dongguan City, Guangdong Province
 Yue Gong Wang An Bei No. 4419002007491